The read
Last week the equity complex covered and the currency shorts did not move. This week both went the other way. Leveraged funds sold the S&P 500, the Nasdaq-100 and the Russell 2000 together, taking the Nasdaq short to 30.1% of open interest and a COT Index of zero, while the Japanese yen short, which grew by 5,805 contracts only a week ago, was cut by 41,165 in a single week. The covering did not stop. It changed hands.
The anchors
ES · CL · GC
ES
Net short 333,099 contracts, or 15.6% of open interest · z +1.24 · COT Index 56 · 1-week flow -30,727 · 4-week flow +31,860Two weeks of covering ended. The short grew by 30,727 contracts and the standardized reading fell from +1.78 to +1.24, though the four-week change is still positive at +31,860. A positive reading against a net short is a statement about where this position sits in its own history, not about which way it is pointing.
CL
Net long 101,050 contracts, or 3.9% of open interest · z +0.61 · COT Index 38 · 1-week flow -7,257 · 4-week flow +26,371WTI gave back a small part of last week's advance. Managed money sold 7,257 contracts after three straight weeks of buying, and the regime moved from Building Long back to Neutral. The four-week change remains positive.
GC
Net long 132,398 contracts, or 27.1% of open interest · z +0.71 · COT Index 55 · 1-week flow +12,070 · 4-week flow +17,544Gold resumed buying after last week's pause, adding 12,070 contracts and moving from Flip Zone to Building Long. At a COT Index of 55 the position is still close to the middle of its own range, and the largest of the three anchors as a share of open interest.
The turn
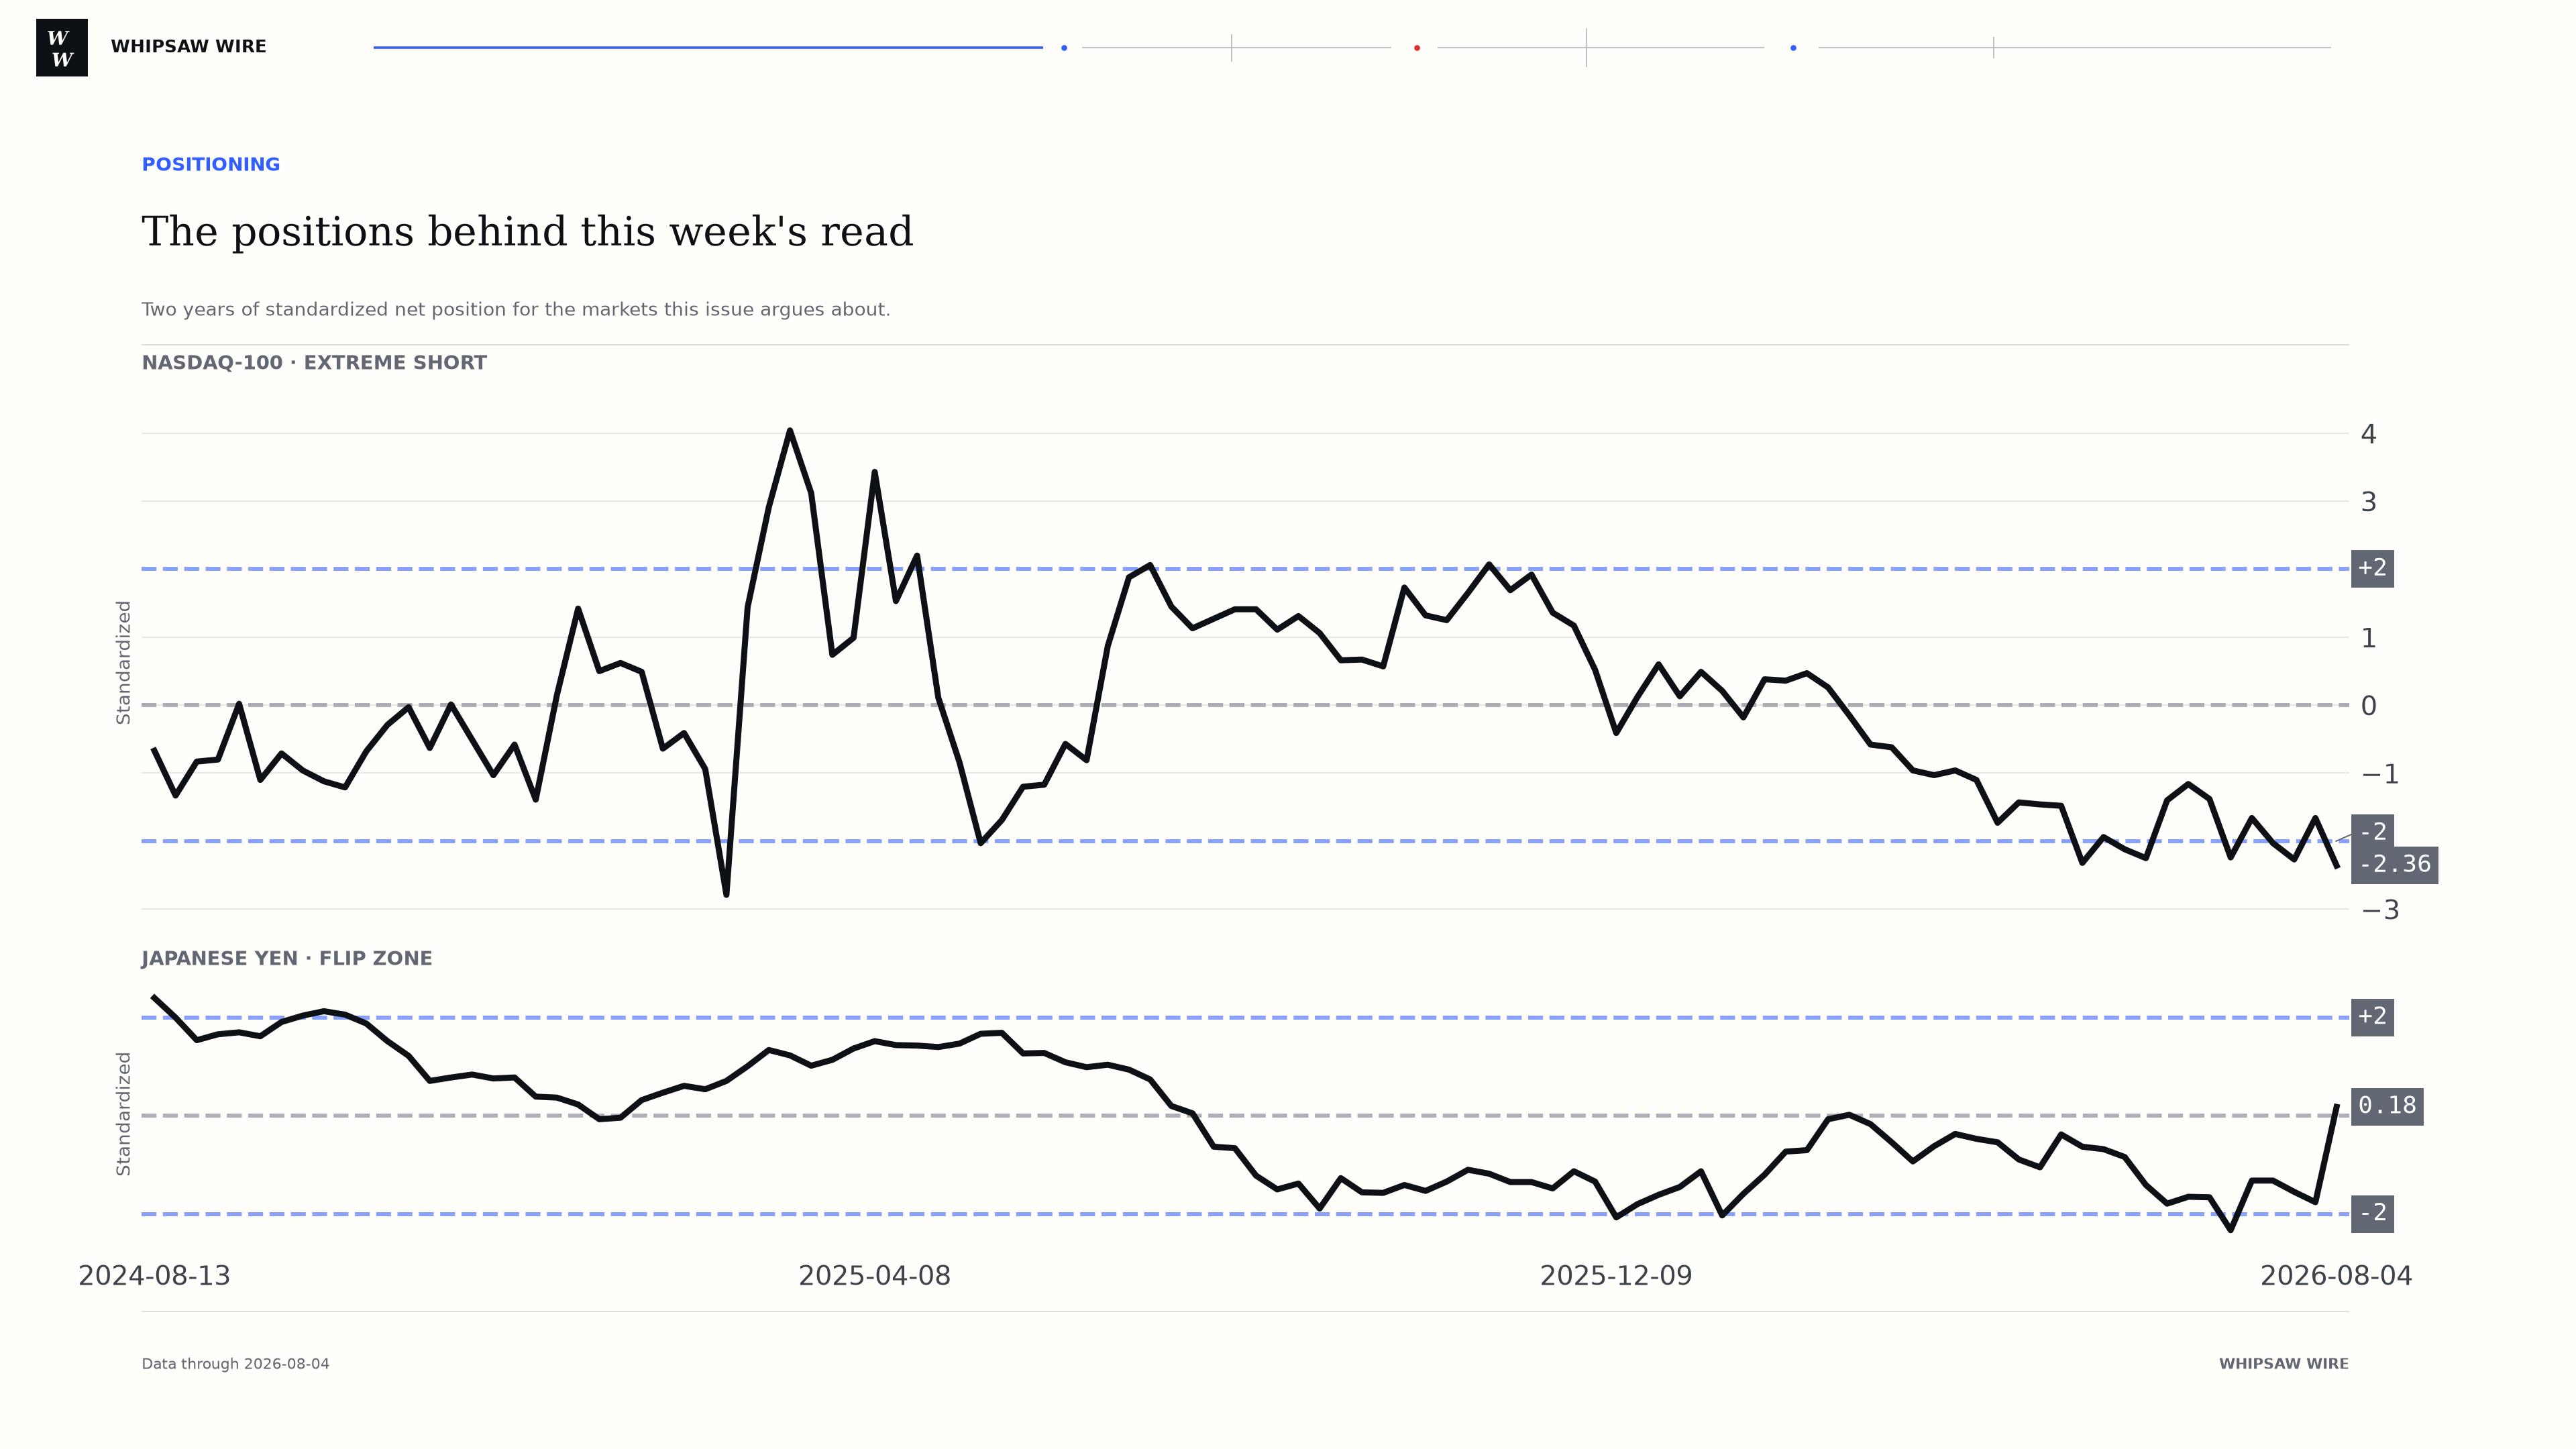
The positions behind this week's read
The move this week
The equity complex sold as one.
The split that closed last week did not reopen. It was replaced by something more uniform. Leveraged funds sold the S&P 500 by 30,727 contracts, the Nasdaq-100 by 23,680 and the Russell 2000 by 10,525, with only the Dow Jones position barely moving at -155. Last week all three covered. This week all three were sold.
The Nasdaq-100 took the worst of it. The net position went from 76,960 short to 100,640 short, the standardized reading fell from -1.66 to -2.36, and the COT Index returned to zero after one week off it. The regime left Accumulating and became Extreme Short. At 30.1% of open interest this is a larger share than the 24.1% the position carried last week, and the four-week change of -32,161 is now negative.
Four things that moved
The changes behind the headline.
Japanese Yen
The largest reading change in the report. Leveraged funds bought back 41,165 contracts, lifting the net from 101,990 short to 60,825 short and moving the standardized reading from -1.76 all the way to +0.18. The regime left Building Short for Flip Zone and the COT Index reached 36. A week ago this same short was still growing, by 5,805 contracts.
Nasdaq-100
Leveraged funds sold 23,680 contracts after covering 13,627 the week before. The COT Index went back to zero and the standardized reading, at -2.36, is now lower than the -2.27 it reached before last week's pause. The step back from the edge lasted one week.
SOFR 3-Month
Last week's largest flow reversed. Leveraged funds sold 86,148 contracts after buying back 248,236, taking the net to 2,532,086 short at 19.3% of open interest. The four-week change is still positive at +340,320, so this is a pause in the unwind rather than its end.
Copper
Managed money bought 11,306 contracts and 17,399 over four weeks, taking the net to 77,796 long and the COT Index to 100, the top of its own range. The standardized reading rose from +0.68 to +1.44 and the regime moved from Neutral to Building Long. Producers and merchants hold the offsetting 92,028 short.
Positioning extremes
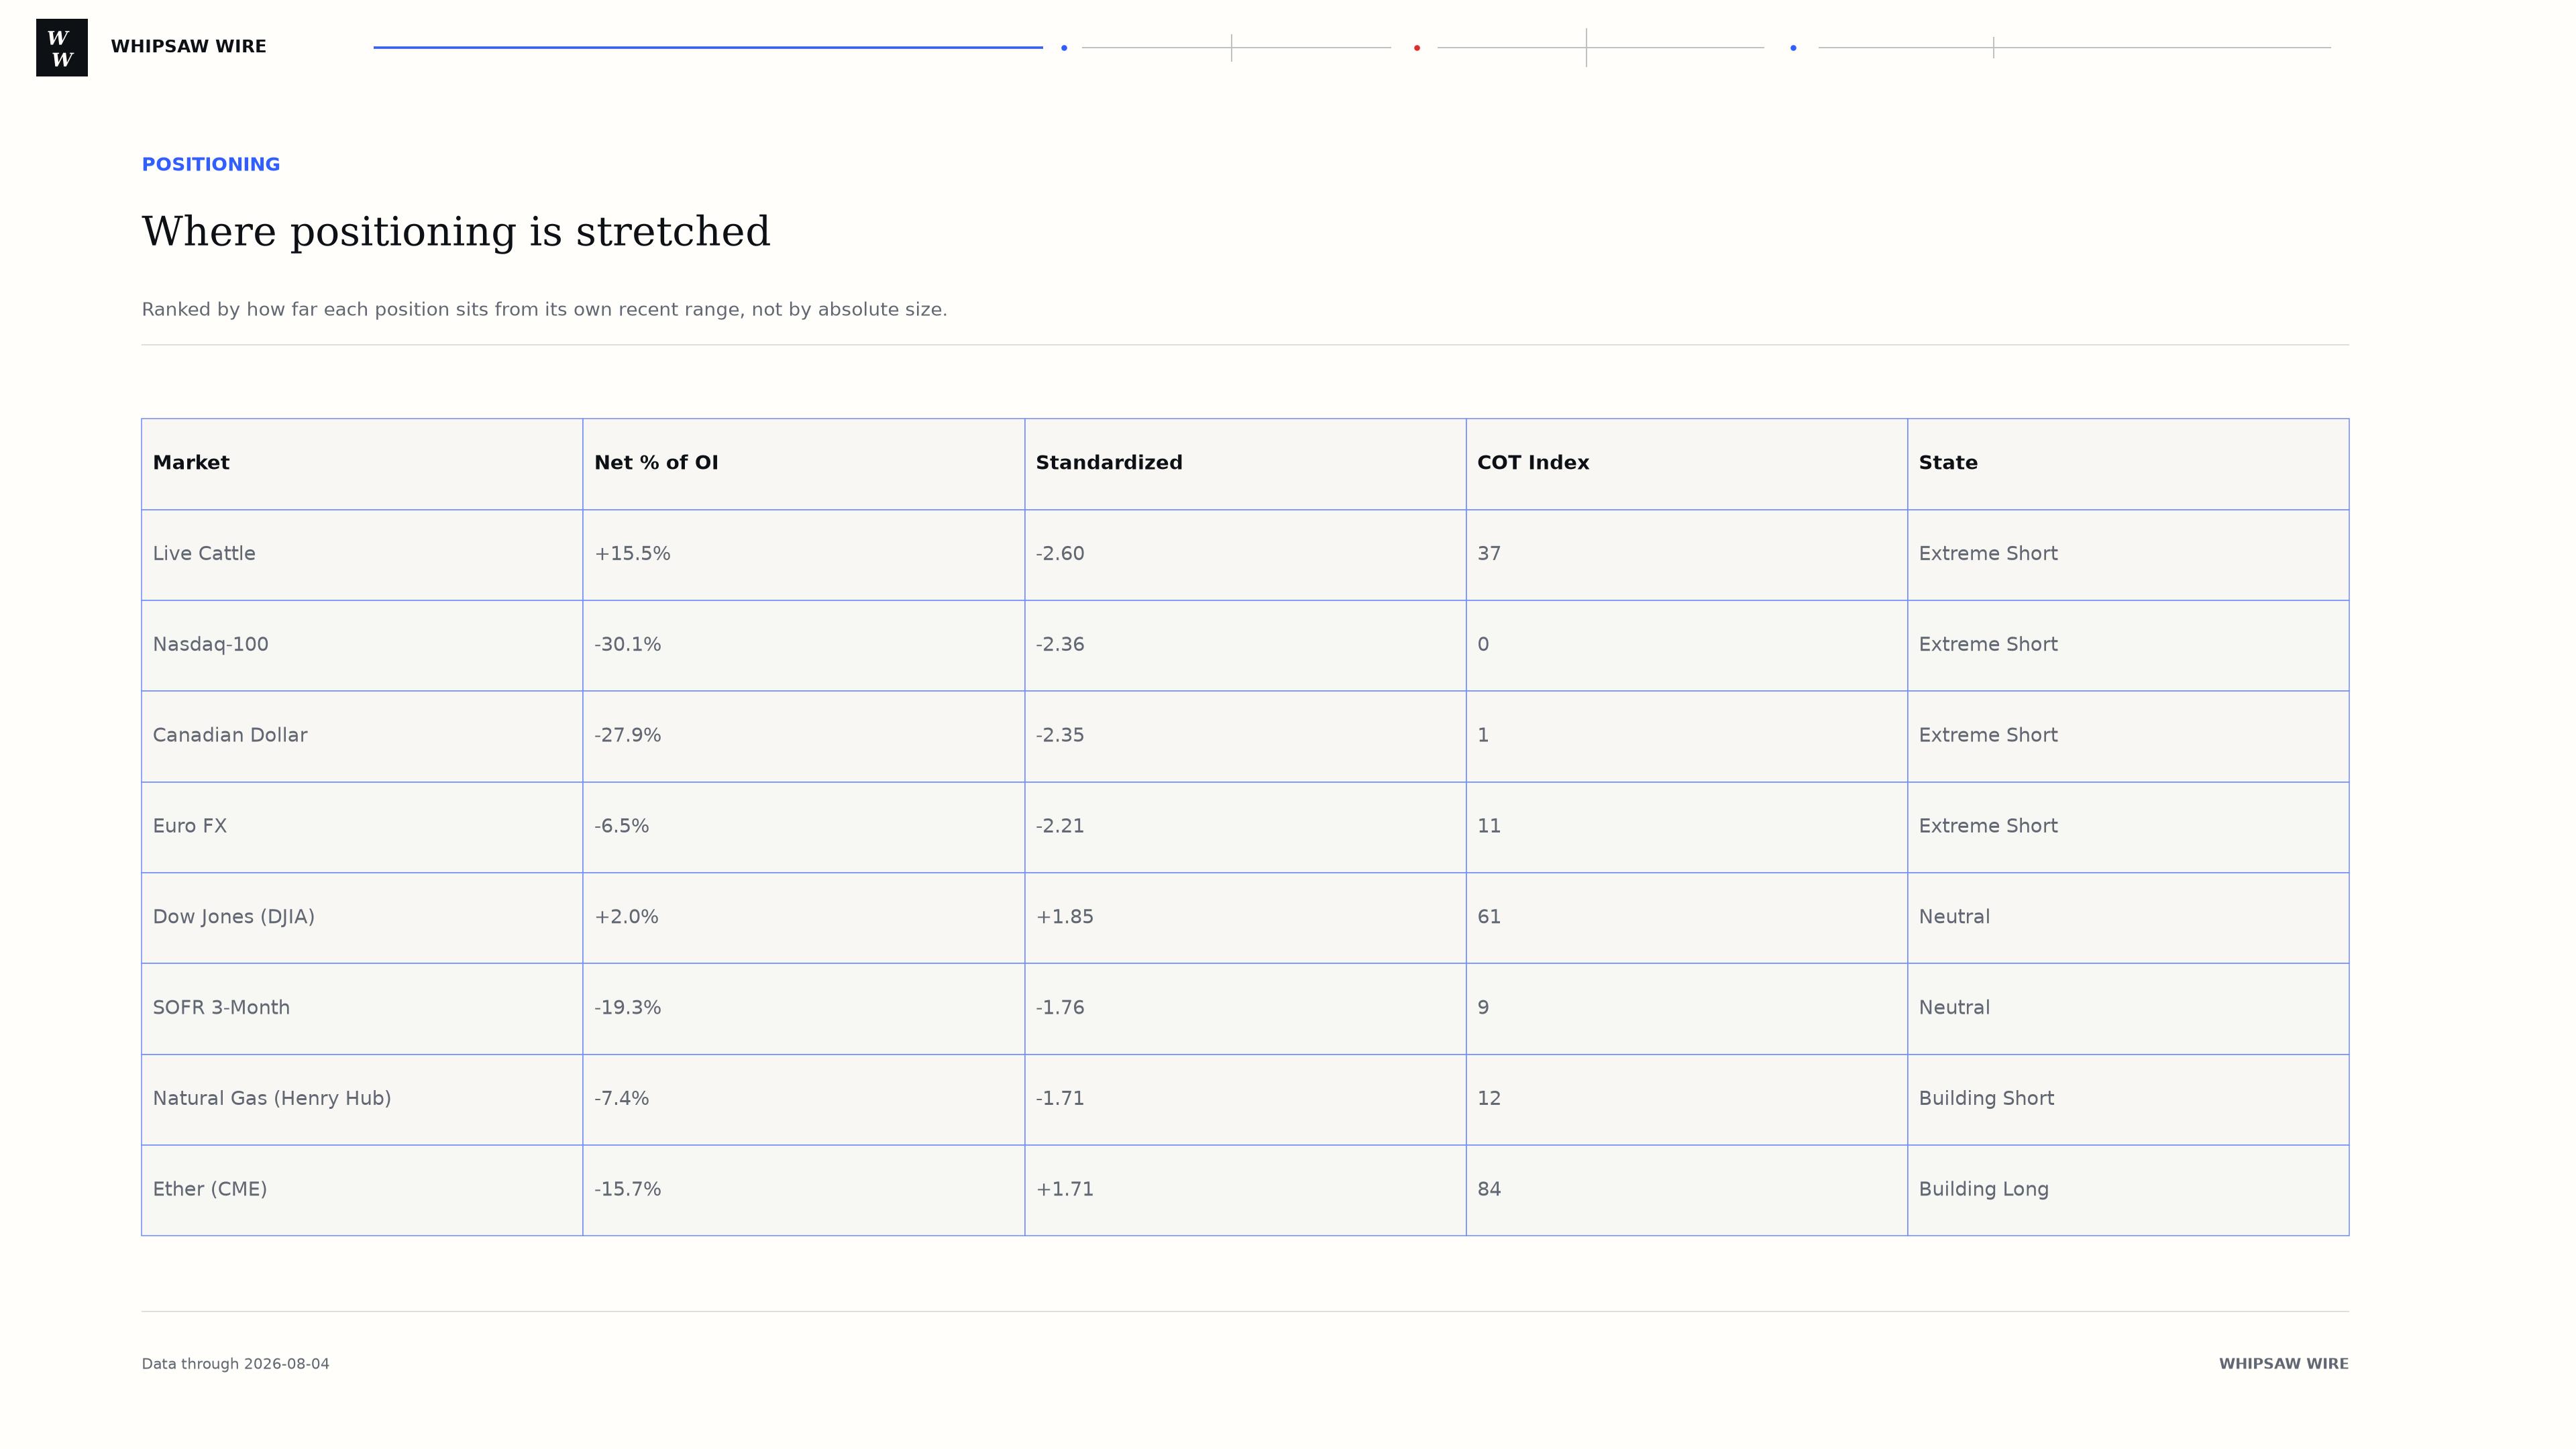
Where the crowd is stretched.
Who is on the other side
The yen short is not only a leveraged fund position.
- Leveraged funds-60,825
- Asset managers-42,422
- Other reportables+76,919
- Dealers+31,423
- Nonreportables-5,095
The week's largest move has an unusual structure. Leveraged funds hold the visible short at 60,825 contracts, but asset managers are short as well at 42,422, which is not how the equity shorts are built. The offsetting long sits almost entirely with other reportables at 76,919, with dealers adding 31,423.
That matters for reading the covering. When the two largest speculative groups are positioned the same way, a move of 41,165 contracts in one week is one side stepping back rather than two sides trading against each other.
The contradiction
The commodity book was bought while equities were sold.
While the equity complex went one way, the commodity side went the other. Copper reached a COT Index of 100, gold moved to Building Long on 12,070 contracts, cotton added 9,869 to reach a COT Index of 81 and its own Building Long, and sugar bought back 34,599 contracts against a net short of 77,814, lifting its standardized reading from +0.74 to +1.44. The exception was natural gas, which sold 20,940 contracts into a new alert at -1.71 and a four-week change of -66,168.
The rates complex disagreed with itself again, in the opposite direction from last week. The front end sold while the long end covered: SOFR gave up 86,148 contracts, and the Ultra T-Bond bought back 12,948 and left Building Short for Neutral at -0.79. Twenty five markets changed regime this week, which is a broad reshuffle rather than a single theme.
One week later
How last week's extremes are tracking.
- SOFR stopped unwinding. After two weeks of covering and a 248,236 contract buyback, leveraged funds sold 86,148 and the regime went from Accumulating back to Neutral.
- The Nasdaq short returned to the edge. Last week it covered 13,627 and left Extreme Short. This week it sold 23,680, went back to a COT Index of zero, and re-entered it.
- Euro FX finally covered. After three weeks at a COT Index of zero, leveraged funds bought back 12,993 contracts and the reading improved from -2.84 to -2.21. It is still an Extreme Short, at a COT Index of 11.
- The Canadian dollar stopped deepening. A change of just 747 contracts after weeks of adding, lifting the reading from -2.56 to -2.35. The COT Index is 1.
- Live cattle stopped selling. Managed money removed only 456 contracts after 8,840 last week, though the four-week change is still -47,254 and the position remains net long 66,067.